Military Home Financing
VA Loan Center
Understanding your VA home loan benefits is an important part of buying a home. From pre-approval and lender comparisons to funding fees and assumable VA mortgages, I help military buyers navigate the purchase process with confidence.
Your VA Benefits
Why Consider a VA Home Loan?
VA-backed mortgages offer valuable financing advantages to eligible service members, Veterans, and certain surviving spouses. Understanding these benefits can help you make informed decisions about your purchase.
Potentially 0% Down
Eligible buyers may qualify to purchase a home without a down payment, subject to lender requirements, appraisal, and other loan conditions.
No Monthly PMI
VA-backed loans do not require monthly private mortgage insurance, which can reduce the monthly cost of homeownership.
Reusable Benefits
Your VA home loan benefit may be used more than once, depending on your remaining entitlement and eligibility.
Getting Started
The VA Loan Pre-Approval Process
Before touring homes, establish your financing strategy and understand your purchasing power. A strong pre-approval helps you prepare for the competitive Washington, D.C., Northern Virginia, and Maryland markets.
Discuss Your Home Buying Goals
We begin with your budget, preferred location, military assignment, commute requirements, and anticipated PCS timeline. I help you understand the local market and prepare for the buying process.
Confirm Your VA Loan Eligibility
Your lender can help obtain your Certificate of Eligibility (COE), review your entitlement, and determine which VA loan requirements apply to your circumstances.
Compare VA-Experienced Lenders
Speak with multiple lenders who regularly handle VA financing. Compare interest rates, annual percentage rates (APR), discount points, lender fees, responsiveness, and closing capabilities.
Obtain Your Pre-Approval
Once your lender reviews your financial documentation, you can establish a realistic price range and begin searching for homes with a clearer understanding of your financing options.
A Personal Example
Comparing VA and Conventional Financing
When I purchased my home in 2023, I asked loan officer Jeff Morelli to compare a VA loan with a conventional mortgage. I wanted to understand whether avoiding the VA funding fee would make a conventional loan the better option.
In that particular comparison, the estimated VA loan payment was $461 less per month, reflecting the interest rate and the absence of monthly private mortgage insurance.
I ultimately chose VA financing. My estimated cash required at settlement was higher because I elected to make a down payment.
This is a historical example from my own purchase, not a current loan quote. The best financing choice depends on today's rates, fees, your eligibility, and your individual circumstances.
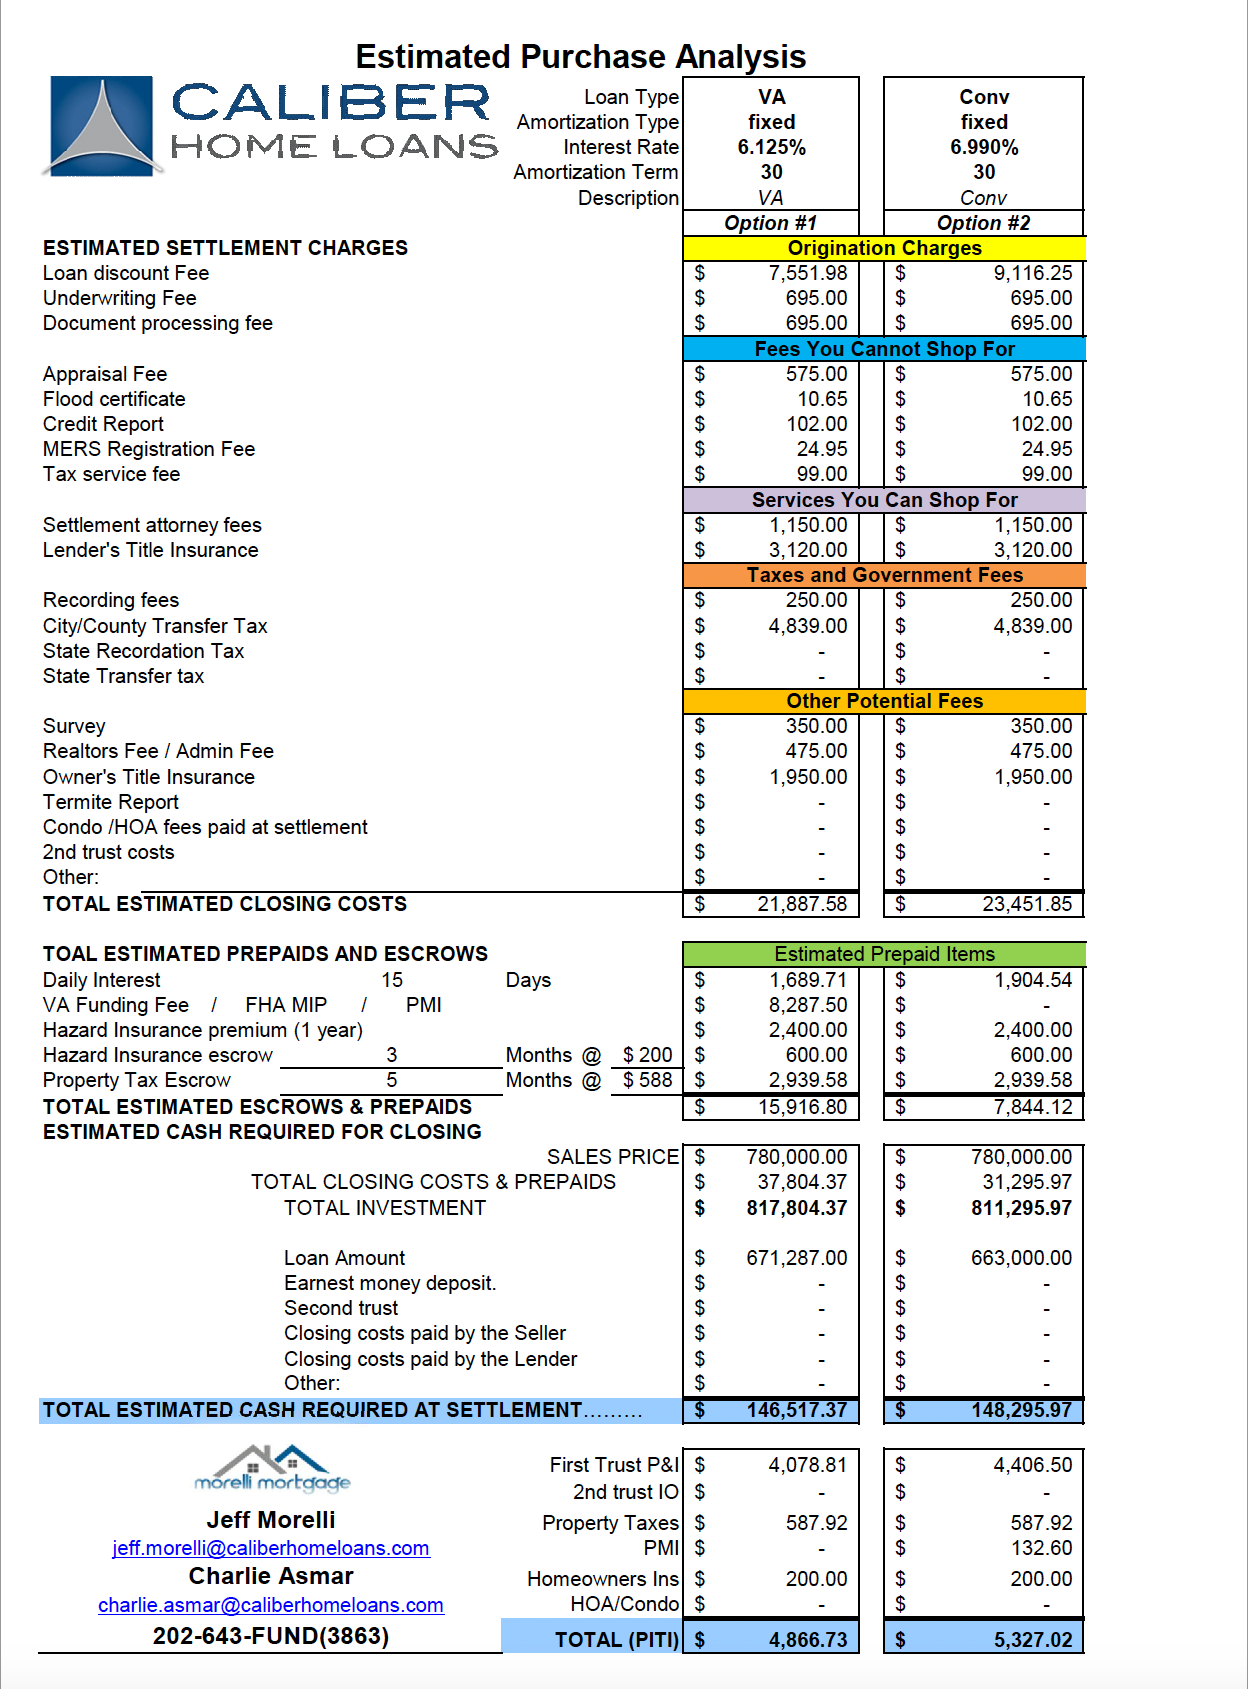
Personal loan comparison prepared in 2023. Figures are specific to that transaction.
Comparing Financing
Look Beyond the Interest Rate
A lender's interest rate is only one part of the financing decision. Review the full Loan Estimate to understand your expected monthly payment and settlement costs.
Interest Rate & APR
Compare the interest rate and annual percentage rate, which reflects interest and certain financing costs.
Origination Fees & Points
Review lender charges, discount points, and whether a lower rate requires additional upfront costs.
Monthly Payment
Consider principal, interest, property taxes, homeowners insurance, and applicable condominium or homeowners association fees.
Cash Required at Closing
Compare your down payment, closing costs, prepaid expenses, deposits, lender credits, and any negotiated seller contributions.
VA Mortgage Rate Trends
30-Year Fixed Rate Veterans Affairs Mortgage Index
The chart below illustrates historical VA mortgage interest rate trends, providing valuable insight into how rates fluctuate over time. Mortgage rates are influenced by economic conditions, financial markets, and lender pricing.
Source: Federal Reserve Economic Data (FRED) . Historical index data, not a personalized mortgage rate quote.
Why Mortgage Rate Timing Matters
Mortgage interest rates can change daily, sometimes even during the same day. The rate available when you begin searching for a home may differ from the rate offered when you are ready to purchase.
Once your purchase offer is accepted and the contract is signed by the seller, I will promptly provide the ratified contract to your lender so we can coordinate the next steps in your financing process.
Your lender will explain when your interest rate can be locked and the available lock periods. A rate lock generally protects your agreed-upon interest rate from market increases during the specified period, provided the loan closes before the lock expires and the loan terms remain unchanged.
Budgeting for Your Purchase
VA Loan Out-of-Pocket Costs
While a zero-down VA loan covers 100% of the home's purchase price, buyers still need cash on hand during the transaction for out-of-pocket expenses—specifically earnest money, home inspection fees, and closing costs.
Earnest Money Deposit
The earnest money deposit is due within 5 days of going under contract. The exact amount is negotiated in the purchase agreement and will be credited toward your total cash needed at closing.
Home Inspection
A home inspection checks for any problems with the house. For a VA loan, you also have to get a termite inspection. You pay for these out of pocket, and the price depends on the home's size.
VA Appraisal
A VA loan requires an appraisal to check the home's value and safety, which the buyer pays for. Keep in mind, an appraisal is not the same thing as a home inspection.
Closing Costs
Closing costs can include lender fees, title charges, recording fees, taxes, insurance, and prepaids. Your lender will give you a detailed estimate for your specific loan.
Understanding VA Loan Costs
VA Funding Fee
Most VA purchase loans include a one-time funding fee unless the borrower qualifies for an exemption. The amount depends on factors including first or subsequent use and the down payment.
| Down Payment | First Use | Subsequent Use |
|---|---|---|
| Less than 5% | 2.15% | 3.30% |
| 5% or more | 1.50% | 1.50% |
| 10% or more | 1.25% | 1.25% |
Rates shown are VA purchase-loan funding fee rates effective April 7, 2023. Verify current rates with your lender or the Department of Veterans Affairs.
Who May Qualify for an Exemption?
Certain borrowers are exempt, including qualifying Veterans receiving or eligible for service-connected disability compensation, certain surviving spouses receiving Dependency and Indemnity Compensation, and eligible active-duty Purple Heart recipients. Other VA exemption categories may apply.
An Alternative Financing Opportunity
VA Loan Assumptions
A VA loan assumption lets you take over the seller’s current home loan—including the exact interest rate they got when they bought the house. If the seller locked in a low interest rate a few years ago (like 3%), you get to keep that low rate instead of getting a new loan with today’s higher rates. You take over their monthly payments, but you still have to apply, qualify with their lender, and pay the seller the cash difference between what the home is worth and what they still owe on the mortgage. Taking over a past, lower rate keeps your monthly bill much smaller than getting a brand-new loan today.
I have experience helping buyers and sellers navigate VA and FHA loan assumptions.
Before You Assume
Civilian Buyers Can Assume a VA Loan—But There’s a Major Catch for the Seller
When a non-veteran takes over the mortgage, the seller’s VA entitlement used for that loan remains tied to the property until the loan is fully paid off. That portion of the seller’s benefit is unavailable for another purchase, which may leave them without enough remaining entitlement to buy their next home with $0 down.
You can take over the seller’s existing interest rate, which may be lower than current rates, without needing military service. You must still qualify financially and receive approval from the lender or loan servicer.
Unless an eligible veteran with sufficient entitlement assumes your loan and completes a Substitution of Entitlement, the entitlement used for that mortgage remains tied up until the loan is paid in full. Your remaining entitlement determines whether another VA purchase may require a down payment.
My Experience Beyond VA Financing
FHA Loan Assumptions
My experience with assumable mortgages extends beyond VA loans. I have helped many buyers purchase homes by assuming an existing FHA loan, taking over the seller’s remaining mortgage balance, interest rate, and remaining loan term.
FHA assumptions can be less complex than VA assumptions because there is no military entitlement to protect or substitute. In my experience, removing that additional layer can make the process more straightforward for both buyers and sellers.
I help buyers evaluate the existing loan, understand the equity gap, and coordinate with the loan servicer throughout the assumption process.
Choosing Your Financing Partner
Selecting a VA-Experienced Lender
A lender's experience with VA transactions matters, particularly when buying in a competitive market or working around military relocation deadlines.
Compare Several Lenders
I encourage buyers to speak with at least three lenders and compare Loan Estimates for similar loan terms. Review rates, APR, discount points, and lender fees.
Evaluate Communication
Choose a lender who responds promptly, explains financing options clearly, and coordinates effectively with your real estate agent and settlement company.
Consider Local Experience
Familiarity with Washington, D.C., Northern Virginia, and Maryland contracts, settlement practices, and VA appraisal requirements can be valuable.
Review the Complete Offer
A lower advertised interest rate does not always mean lower overall borrowing costs. Evaluate lender credits, points, fees, and your expected ownership timeline.
Beyond the Mortgage
VA Financing Is Only Part of the Purchase
As a full-time Military Realtor®, I help service members and military families navigate the real estate transaction alongside their financing and PCS requirements.
Personalized Real Estate Guidance
Ready to Buy With Your VA Benefits?
Whether you're preparing for a PCS, buying with a VA loan, or exploring an assumable mortgage, let's discuss your goals and develop a strategy that fits your needs.